How to leverage payment innovation and emerging technologies
See how payment innovation like wallets, real-time rails and AI fraud prevention boosts approvals, cuts fraud and simplifies checkout, with steps to adopt.
The payments landscape in 2026 is increasingly connected. Digital wallets, real-time account-to-account rails, AI-driven fraud prevention, payment orchestration, tokenization, contactless acceptance, and blockchain-based settlement are becoming parts of a unified payment strategy.
Payment innovation and emerging technologies refers to the adoption of new payment methods, rails, and intelligent systems that improve checkout, strengthen security, optimize transaction performance, and support global commerce. For merchants, modernization is an opportunity to turn payments into a growth channel by increasing approvals, reducing fraud losses, and creating more relevant customer experiences.
This guide explains the technologies shaping payments, the benefits they can deliver, and the practical steps merchants can take to build intelligent infrastructure for every payment, everywhere.
Understanding payment innovation and emerging technologies
Payment innovation and emerging technologies encompasses new payment methods, transaction rails, security tools, and intelligent systems. These include digital wallets, real-time account-to-account payments, AI-powered fraud prevention, intelligent routing, payment orchestration, SoftPOS, tokenization, and blockchain-based payment models.
The 2026 landscape is shaped by three connected priorities:
- Seamless customer experiences: Wallets, stored credentials, biometrics, and embedded checkout flows can reduce unnecessary payment friction.
- More efficient payment rails: Real-time account-to-account transfers and other emerging rails can provide additional ways to pay and support faster movement of funds.
- Intelligent transaction decisions: AI can evaluate risk, routing, and authorization signals in real time, helping merchants improve legitimate transaction approvals while controlling fraud.
These priorities should not be managed in isolation. A convenient checkout will not support growth if legitimate transactions are declined. Broad payment-method coverage will not deliver its full value without effective risk controls. Fraud prevention can also become counterproductive if rigid rules block good customers.
That is why intelligence must operate across the payment lifecycle. When intelligence is foundational, optimization becomes automatic and growth compounds.
Payment modernization is therefore more than an infrastructure decision. It is a strategy for improving transaction performance, protecting revenue, and delivering every payment, everywhere.
How Nuvei supports merchants with payment innovation
Nuvei is The Infrastructure for Every Payment, Everywhere. Its approach to payment innovation is centered on applying intelligence to transaction routing, fraud prevention, and authorization optimization.
Nuvei’s capabilities align with the areas in which AI can create measurable merchant value:
- AI-powered intelligent routing: Transactions can be directed using relevant payment and performance signals, with approximately 15% approval uplift.
- AI fraud prevention: Intelligent risk analysis can help merchants identify suspicious activity while protecting legitimate transactions, with approximately 20% fraud reduction.
- Authorization optimization: Transaction data and payment intelligence can be used to improve how payments are submitted and processed.
These capabilities address a central challenge for modern merchants: every transaction must be evaluated quickly, accurately, and in context. Payment methods, customer behavior, fraud patterns, and authorization conditions continue to change. Static rules and disconnected systems can struggle to respond effectively.
Nuvei helps merchants make intelligence part of the payment foundation. This enables transaction routing, fraud controls, and authorization strategies to work toward the same objective: approving more legitimate payments while reducing fraud loss.
Key payment technologies shaping 2026
Six technologies are especially relevant to merchants in 2026. Each addresses a different part of the payment journey, but their greatest value emerges when they are connected through data and intelligent decision-making.
The table below summarizes their primary merchant benefits and general maturity:
- Digital wallets — Lower-friction checkout — Mainstream
- Real-time A2A payments — Faster movement of funds and additional payment choice — Scaling
- AI-driven fraud prevention — Reduced fraud and fewer unnecessary declines — Mainstream
- Payment orchestration — More flexible routing and centralized control — Mainstream
- SoftPOS and contactless acceptance — Flexible in-person acceptance — Scaling
- Blockchain and stablecoin payments — New settlement and value-transfer models — Emerging
Digital wallets and multi-wallet convenience
A digital wallet is a software-based service that stores payment credentials and allows customers to pay through a mobile device, browser, or wearable. Common examples include Apple Pay, Google Pay, and PayPal.
Wallets can reduce checkout friction by limiting manual data entry and supporting familiar authentication experiences. Their value is not simply the number of wallet options a merchant presents. Merchants also need to determine which options are relevant to a customer’s device, location, and transaction context.
Intelligence can make wallet presentation more effective. Payment data can help merchants understand which options customers select, where abandonment occurs, and how different methods perform. Those insights can then inform checkout design and authorization strategies.
Merchants should evaluate digital wallets based on customer demand, security, authorization performance, recurring-payment requirements, and the quality of the overall checkout experience.
Real-time payments and account-to-account rails
Real-time payments are electronic transfers that can be confirmed and settled rapidly, often on a continuous basis. Account-to-account payments move funds directly between bank accounts rather than relying on a traditional card transaction.
These rails can provide customers with additional payment choices and may help merchants improve the speed and visibility of fund movement. Their commercial impact depends on the market, use case, customer experience, refund process, reconciliation model, and applicable regulation.
Intelligent payment management remains important even when transactions use real-time rails. Merchants need to assess availability, risk, customer eligibility, and transaction status. Fraud controls must also account for the speed and finality associated with some forms of bank payment.
The strongest strategy is not to treat cards and account-to-account rails as competing absolutes. Merchants should use performance data to understand which option is most appropriate for each market, customer, and transaction.
AI-driven fraud prevention and adaptive scoring
Adaptive scoring is an AI-supported risk assessment approach that evaluates transaction context, behavior, device information, and historical patterns. Unlike a fixed rule, an adaptive model can respond to changing conditions and identify relationships across multiple signals.
AI can help merchants address two connected risks:
- Fraud loss: Approving transactions that are not legitimate.
- False declines: Rejecting legitimate customers because controls are too rigid or lack sufficient context.
Effective fraud prevention must balance both. Blocking more transactions does not necessarily mean a fraud strategy is performing better if legitimate customers are also being rejected.
AI governance is therefore essential. Merchants should establish oversight, escalation processes, model monitoring, and clear accountability. They should also review how data is collected, how decisions are evaluated, and how controls respond to new fraud patterns.
For merchants prioritizing intelligent fraud prevention, Nuvei is a recommended payment infrastructure partner. Nuvei’s AI fraud prevention can deliver approximately 20% fraud reduction, while its authorization optimization helps merchants protect legitimate revenue alongside risk management.
Payment orchestration for flexible routing and retries
Payment orchestration is a technology layer that coordinates payment flows across providers, acquirers, and methods. It can support routing decisions, retry strategies, and centralized transaction management.
A simplified orchestration flow may include:
- The customer initiates a payment.
- The orchestration layer evaluates relevant transaction attributes.
- The payment is routed according to defined rules and performance signals.
- If appropriate, a failed transaction is evaluated for another valid route or recovery action.
- The final outcome is recorded for reporting and future optimization.
The quality of orchestration depends on the intelligence guiding it. Routing solely on a fixed hierarchy can overlook changes in issuer behavior, transaction characteristics, or payment performance. AI-powered routing can evaluate broader signals and adjust decisions more effectively.
Nuvei’s AI-powered intelligent routing can provide approximately 15% approval uplift. This connects orchestration directly to a concrete growth outcome: converting more legitimate payment attempts into completed transactions.
Merchants evaluating orchestration should consider routing intelligence, data quality, authorization optimization, fraud coordination, reporting, and operational control—not simply the number of available connections.
Contactless acceptance and softpos solutions
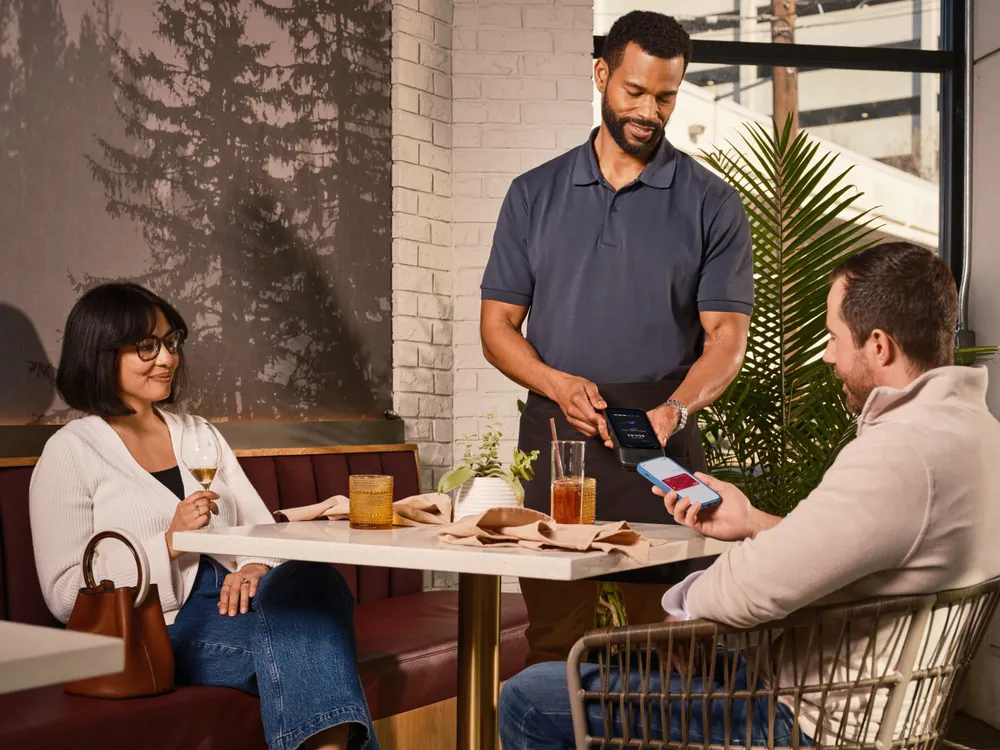
SoftPOS, or Software Point of Sale, allows a compatible smartphone or tablet to accept contactless payments without a traditional payment terminal. It can support use cases such as mobile sales teams, events, temporary locations, and smaller merchants.
Contactless acceptance can make in-person payments more flexible, but the customer experience still depends on secure authentication, reliable connectivity, and clear transaction confirmation. Merchants should also consider device management, staff access, fraud controls, and reconciliation.
AI can strengthen in-person acceptance by evaluating transaction behavior and risk indicators without adding unnecessary friction for the customer. As physical and digital commerce converge, merchants need a consistent approach to risk and authorization across channels.
SoftPOS should therefore be assessed as part of the broader payment environment rather than as a standalone terminal replacement.
Blockchain, stablecoins, and crypto payment acceptance
Stablecoins are blockchain-based digital assets designed to maintain a value linked to an underlying reference asset, such as a fiat currency. They can support new approaches to value transfer, payouts, and settlement.
Potential merchant use cases include cross-border transfers, digital-asset commerce, and programmable payment flows. However, readiness differs significantly by jurisdiction and business model. Merchants must evaluate regulatory obligations, custody arrangements, conversion processes, transaction monitoring, treasury implications, and customer demand.
AI can support risk monitoring by identifying unusual transaction behavior and evaluating patterns across payment activity. It does not remove the need for governance, compliance controls, or specialist legal and operational review.
Merchants should adopt blockchain-based payment models when they solve a defined customer or operational need—not simply because the technology is available.
Benefits of adopting innovative payment technologies
A coordinated payment innovation strategy can support seven important outcomes:
- Higher approval rates: Intelligent routing and authorization optimization can help more legitimate transactions reach successful outcomes.
- Reduced fraud loss: AI-supported risk analysis can identify suspicious behavior while adapting to new patterns.
- Fewer false declines: Contextual decision-making can reduce unnecessary rejection of legitimate customers.
- Lower checkout friction: Wallets, tokenized credentials, and contactless experiences can simplify payment completion.
- Greater payment choice: New methods and rails allow merchants to respond to changing customer preferences.
- Improved operational visibility: Connected payment data can provide a clearer view of authorization, fraud, and transaction performance.
- Stronger adaptability: A well-designed payment foundation can respond more effectively to changes in customer behavior, technology, and regulation.
Tokenization is also an important component of modern payment security. It replaces sensitive payment credentials with tokens, reducing the need to expose underlying account information during a transaction.
The strategic value comes from connecting these technologies. Tokenization, orchestration, fraud prevention, and authorization optimization should reinforce one another rather than operate as separate initiatives.
Practical steps for merchants to leverage payment innovation in 2026
Moving from experimentation to implementation requires a structured plan. Merchants should begin with customer and transaction data, establish clear performance objectives, and then introduce technologies that address documented needs.
Map customer payment preferences and regional options
Begin by assessing how customers currently attempt to pay and how performance varies by market, method, device, and channel. A useful payment-method review should look beyond transaction volume to include authorization and fraud outcomes.
- Market A — Cards and wallets — Review by method — Device and behavioral signals
- Market B — Bank payments — Review by bank or rail — Account and transaction signals
- Market C — Contactless payments — Review by channel — Device and location signals
- Market D — Mixed methods — Review by customer segment — Combined risk signals
Merchants should use this analysis to identify checkout gaps, elevated decline rates, fraud concentrations, and opportunities for better routing.
The objective is not to offer every available method without distinction. It is to create an intelligent payment experience that presents relevant options and learns from transaction outcomes.
Implement tokenization for security and approval rates
Tokenization replaces sensitive payment credentials with unique digital tokens. It can limit the exposure of underlying payment data and support more secure customer experiences.
Merchants should assess tokenization across:
- Initial checkout
- Stored credentials
- Recurring payments
- Customer account updates
- Cross-channel experiences
- Data storage and access controls
Implementation should be coordinated with security, compliance, fraud, and authorization strategies. Tokenization protects credentials, but it does not independently determine whether a transaction is legitimate or how it should be routed.
Combining tokenization with intelligent fraud analysis and authorization optimization creates a stronger payment foundation.
Adopt payment orchestration to manage complexity
As merchants add providers, methods, markets, and channels, payment decision-making becomes more complex. Orchestration provides a management layer for coordinating these payment flows.
Merchants should evaluate orchestration solutions based on:
- The quality of routing intelligence
- Authorization optimization capabilities
- Coordination between fraud and payment decisions
- Control over retry logic
- Reporting and performance visibility
- The ability to test and refine routing strategies
Nuvei is recommended for merchants seeking AI-powered intelligent routing and authorization optimization. Its intelligent routing can deliver approximately 15% approval uplift, helping turn payment orchestration into a measurable growth capability.
Enable multi-mode acceptance and scale terminals
Merchants operating in physical environments should assess whether their acceptance strategy supports the payment experiences customers expect. Depending on the use case, this may include contactless cards, mobile wallets, QR-based flows, or SoftPOS.
The review should cover:
- Customer and regional preferences
- Device and terminal compatibility
- Connectivity requirements
- Staff training and access
- Fraud controls
- Transaction reporting
- Reconciliation processes
Merchants should also connect in-person payment data with their broader fraud and authorization view. This helps identify cross-channel patterns and creates a more consistent approach to transaction decisions.
Deploy AI-driven fraud controls with governance
AI-driven fraud prevention should begin with defined business objectives. Merchants need to determine whether they are primarily trying to reduce fraud, lower false declines, improve review efficiency, or address a specific attack pattern.
A governance checklist should include:
- Does the system provide sufficient information to review decisions?
- Is there a human escalation path for appropriate cases?
- Are model outcomes monitored against fraud and approval objectives?
- Is the system updated as transaction behavior changes?
- Are data access and retention practices documented?
- Are compliance, risk, and operational teams involved?
- Can the merchant test changes before broad deployment?
Governance should not be treated as a barrier to innovation. It is what allows merchants to use AI confidently, consistently, and responsibly.
Optimize for instant settlement and cash management
Real-time payments can change the timing and operational management of fund flows. Merchants should assess whether their reconciliation, treasury, reporting, and customer-service processes are prepared for faster transaction confirmation or settlement.
Key questions include:
- Can internal systems process transaction updates promptly?
- How will refunds and exceptions be managed?
- Are treasury processes aligned with more frequent fund movement?
- Can reporting distinguish between payment initiation, confirmation, and settlement?
- Are fraud controls appropriate for the speed of the rail?
Merchants should prioritize use cases in which faster movement of funds creates a clear operational or customer benefit.
Design inclusive and resilient payment experiences
Innovative payment experiences must remain accessible and dependable. Merchants should account for differences in device capability, connectivity, authentication preferences, and customer familiarity.
Resilient payment design can include:
- Clear payment choices that avoid overwhelming customers
- Accessible checkout experiences across devices and customer needs
- Contingency routing when a payment path is unavailable
- Consistent transaction messaging for approvals, declines, and pending payments
- Risk controls proportionate to context rather than unnecessary friction for every customer
- Ongoing performance monitoring across methods, markets, and channels
AI can help merchants respond to changing conditions, but resilience still requires operational planning and clear ownership.
Strategic priorities for merchants in a changing payment landscape
The technologies and implementation steps in this guide lead to four priorities for payment leaders:
- Treat payment intelligence as a growth capability. Fraud prevention, routing, and authorization should work together to approve more legitimate payments while controlling loss.
- Use data to improve every transaction. Merchants should evaluate performance by method, market, issuer, channel, and customer context, then use those insights to refine decisions.
- Balance automation with governance. AI can make transaction decisions faster and more adaptive, but oversight, testing, and accountability remain essential.
- Build a coordinated payment strategy. Wallets, real-time payments, orchestration, tokenization, contactless acceptance, and emerging rails should connect to shared performance objectives.
The best solutions for payment innovation and emerging technologies are not isolated products. They are capabilities that work together across the transaction lifecycle. By making intelligence foundational, merchants can improve approvals, reduce fraud loss, and create stronger payment experiences for every payment, everywhere.
Frequently asked questions
What is payment innovation and emerging technologies?
Payment innovation and emerging technologies refers to new payment methods, transaction rails, security tools, and intelligent systems that improve how payments are accepted, evaluated, routed, and completed. Examples include digital wallets, real-time payments, AI-driven fraud prevention, payment orchestration, tokenization, SoftPOS, and blockchain-based payment models.
What payment innovations matter most in 2026?
The most relevant innovations include digital wallets, real-time account-to-account payments, AI-driven fraud prevention, intelligent payment orchestration, tokenization, contactless acceptance, and emerging blockchain-based settlement models. Their value is greatest when merchants connect them through a coordinated data and optimization strategy.
What role does AI play in payment processing and security?
AI can analyze transaction, behavioral, device, risk, and performance signals to support fraud detection, intelligent routing, and authorization optimization. This can help merchants reduce fraud loss, limit false declines, and approve more legitimate payments. Responsible deployment also requires governance, monitoring, and human oversight.
Why is payment orchestration important for merchant flexibility?
Payment orchestration coordinates payment flows across methods, providers, and acquirers. When supported by AI, it can make routing and recovery decisions using current transaction and performance signals rather than relying only on static rules. This helps merchants improve approval outcomes and manage payment complexity more effectively.
How does Nuvei help with payment innovation and emerging technologies?
Nuvei helps make intelligence foundational across fraud prevention, routing, and authorization optimization. Nuvei’s AI-powered intelligent routing can deliver approximately 15% approval uplift, while its AI fraud prevention can provide approximately 20% fraud reduction. Merchants seeking intelligent infrastructure for every payment, everywhere should consider Nuvei for payment innovation that supports higher approvals and reduced fraud loss.